The Ledger in the Drawer: Institutional Memory and the Family Firm Advantage
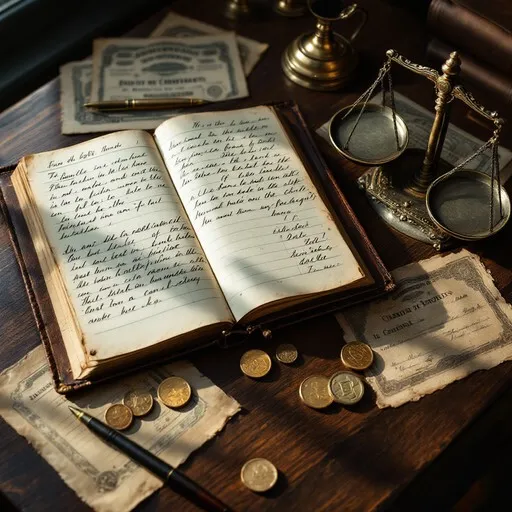
Photo: old handwritten business ledger book on wooden desk vintage, via images.stockcake.com
In the back office of a family-run wholesale distributor outside Akron, there is a shelf of bound ledgers going back to 1968. The early volumes are handwritten: not just invoices and payroll, but margin notes. A customer who paid late during the 1975 downturn but never defaulted. A supplier whose quality slipped after a change in ownership, flagged in pencil and confirmed two years later. A note, in a grandfather's hand, explaining why the company declined a lucrative contract in 1983.
Most private equity-backed competitors of this firm could not produce an equivalent record if their valuation depended on it. In one sense, of course, they can produce far more: dashboards, cohort analyses, retention curves, real-time everything. But the ledger and the dashboard record different things. The dashboard records what happened. The ledger records what it meant, and why the firm chose as it did.
The Understated Asset of Remembering Why
Institutional memory, as the term is used in most corporations, means documents. Family firms tend to understand it as narrative. The distinction matters because decisions decay into data very quickly. A pricing decision made in 2009 is, on a dashboard, a number. In a family firm, it is a story: the recession, the customer who would have been lost, the argument at Sunday dinner, the resolution that held for a decade.
That story does work no number can. It constrains future decisions without requiring a policy manual. When a third-generation manager considers a similar move, the reasoning arrives pre-loaded—not as a rule to obey but as a precedent to weigh. This is why family firms often appear to make decisions faster than their process should allow. They are not deciding from scratch. They are consulting a memory.
Skeptics will object, reasonably, that the same closeness breeds insularity, and sometimes it does. Family firms are also where grudges outlive their usefulness and where "we've always done it this way" hardens into doctrine. The asset and the liability share a root. But the failure mode is manageable; the amnesia of the dashboard is not, because you cannot retrieve what was never written down.
What the Modern Company Can Steal
None of this requires a founding family. It requires habits that most organizations abandoned in the name of scale, and could resume tomorrow.
Write decisions as letters, not tickets. The founder's letter is a family-firm staple: a document addressed to successors explaining not just what was decided but what was feared and what was hoped. A quarterly version of this—a page from leadership to the future—costs an hour and compounds for decades.
Keep a decision log with the reasoning attached. Not the outcome; the reasoning. Six months later, annotate it with what actually happened. The gap between expectation and result is where an organization's real strategy lives.
Let the record keep the people. Handwritten ledgers endure partly because they carry the author's presence—hesitations, emphases, the occasional crossed-out mistake. Digital records flattened into templates lose this. A deliberate note in the author's own register, unpolished, is more likely to be trusted and reread than a polished summary.
Treat memory as succession planning. When a longtime employee departs, most companies run an exit interview and call it knowledge transfer. Family firms assume the knowledge was already written down, over years, in the ordinary course of work. The transfer happened continuously or not at all.
The Long Compounding
There is a reason the phrase "standing on the shoulders of giants" comes from scholarship rather than commerce: businesses rarely think of themselves as accumulating understanding across generations. The family firm, almost by accident, does. Its ledgers and letters form a slow, idiosyncratic, deeply local body of knowledge that no acquirer can diligence and no competitor can download.
Private capital will continue to consolidate American main streets, and many of those transactions will create real value. But the acquirers should know what they are buying and what they are not: the inventory transfers at closing, but the memory does not—not unless someone thought, decades earlier, to write it down in a form a stranger could someday read.